
Inflation, Competing Priorities, and Uncertainty Erode Retirement Security
PR Newswire
LOS ANGELES, Oct. 28, 2026
New report examines the retirement outlook for four generations of workers
LOS ANGELES, Oct. 28, 2026 /PRNewswire/ — Most American workers (78%) agree that today’s high cost of living is making it harder for them to save for retirement, according to Stressed and Strained: Four Generations Strive for Retirement Security, a new report by the nonprofit Transamerica Center for Retirement Studies® (TCRS) in collaboration with Transamerica Institute®.
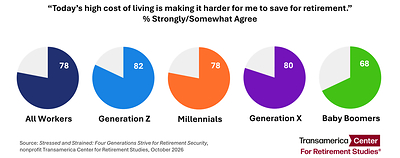
“The U.S. retirement system is evolving, and it now places more responsibility on workers to fund their retirement than it did for prior generations. Today, uncertainty surrounding Social Security’s future, persistent inflation, competing priorities, and potential employment disruptions make it harder for workers to save, plan, and prepare for retirement,” said Catherine Collinson, CEO and president of Transamerica Institute and TCRS. “It is a perfect storm.”
Almost two in three workers (65%) agree with the statement, “I could work until retirement and still not save enough to meet my needs,” according to the survey’s findings. Seventy-three percent are concerned that Social Security will not be there for them when they are ready to retire. Meanwhile, 41% cite outliving their savings and investments as one of their greatest retirement fears.
Stressed and Strained: Four Generations Strive for Retirement Security is a survey-based research report offering an in-depth examination of the retirement preparedness of workers across generations, including Generation Z, Millennials, Generation X, and Baby Boomers. The report provides insights into their health and well-being, employment, personal finances, and retirement outlook.
Generation Z (Born 1997 to 2012)
“Generation Z workers are starting their careers at a time of unprecedented workforce transformation. It is a critical time for them to establish themselves and their financial footing so that their long-term retirement savings and investments can compound over decades. However, many are balancing their employment with family responsibilities that could hinder their progress,” said Collinson.
Among Generation Z workers who are aged 18 and older, the survey findings include:
- Half of Generation Z workers (50%) are struggling to make ends meet. Twenty-eight percent have more than one job, and 52% have a side hustle.
- Generation Z workers’ current financial priorities include paying off debt (56%), building emergency savings (47%), saving for a major purchase or life event (47%), saving for retirement (40%), and just getting by to cover basic living expenses (40%). Twenty-five percent cite supporting their parents as a priority.
- One in three Generation Z workers (34%) are either currently serving or have served as caregivers for a relative or friend during their working careers. Among them, nine in 10 (90%) have made an adjustment(s) to their work situation because of becoming a caregiver, ranging from missing days of work and reducing hours to forgoing a promotion or quitting a job altogether.
- Generation Z workers have $37,000 saved in their total household retirement accounts (estimated median). One in five (22%) have dipped into their retirement savings by taking a hardship withdrawal and/or early withdrawal from a 401(k) or similar plan or IRA.
Millennials (Born 1981 to 1996)
“Millennials are in their thirties to mid-forties, and many are stretched in their sandwich years of juggling employment, raising children, and caring for aging parents. With so many competing priorities, it may be difficult to find time for retirement planning, but small steps taken today can make a meaningful difference in the long run,” said Collinson.
The survey finds:
- Almost six in 10 Millennial workers (58%) indicate debt is interfering with their ability to save for retirement, and 44% indicate they would prefer not to think about or concern themselves with retirement investing until they get closer to their retirement date.
- Millennial workers’ current financial priorities include paying off debt (61%), saving for retirement (54%), building emergency savings (47%), supporting children (45%), and saving for a major purchase or life event (40%). Sixteen percent cite supporting parents as a financial priority.
- Thirty-seven percent of Millennial workers are currently serving and/or have served as caregivers. Among them, nine in 10 (90%) made an adjustment(s) to their employment because of caregiving.
- Millennial workers have $73,000 saved in their total household retirement accounts (estimated median). One in five (20%) have taken a hardship withdrawal and/or early withdrawal from a 401(k) or similar plan or IRA.
Generation X (Born 1965 to 1980)
“Generation X is entering their sixties and nearing retirement. Many are behind on their savings, which is especially concerning amid persistent inflation. They plan to work longer and retire at an older age to bridge savings gaps, but their success depends on both their financial plans and their ability to safeguard their health and employability,” said Collinson.
The survey finds:
- Eighteen percent of Generation X workers are “very confident” they will be able to fully retire with a comfortable lifestyle, and 25% strongly agree they are building a large enough retirement nest egg.
- More than one in three Generation X workers (36%) expect to retire at age 70 or older or do not plan to retire, and 53% plan to continue working in retirement.
- Almost half of Generation X workers (49%) expect their primary source of retirement income to come from self-funded savings, including 401(k)s, 403(b)s, and IRAs (38%) or other savings and investments (11%). Twenty-seven percent expect to primarily rely on Social Security, while 11% expect to rely on income from continued work, and 5% from a company-funded pension plan.
- Generation X workers have $113,000 saved in their total household retirement accounts (estimated median). Seventeen percent have dipped into their retirement savings by taking a hardship withdrawal or early withdrawal from a 401(k) or similar plan or IRA.
Baby Boomers (Born 1946 to 1964)
“The youngest Baby Boomers are now in their early sixties, and the oldest turn 80 this year. Among those still in the workforce, Baby Boomers are stretching the boundaries of working later in life. They are vulnerable to health and employment issues, so they need contingency plans in case they are forced into retirement unexpectedly,” said Collinson.
The survey finds:
- Over half of Baby Boomer workers (55%) expect to retire at age 70 or older or do not plan to retire.
- Four in 10 Baby Boomer workers (42%) expect Social Security to be their primary source of retirement income, while 27% expect to rely on income from 401(k)s, 403(b)s, and IRAs, and 15% from other savings and investments. Seven percent expect their primary source of income to come from continued work, and 5% from a company-funded pension plan.
- Baby Boomer workers have $263,000 saved in their total household retirement accounts (estimated median). Eleven percent have taken a hardship withdrawal or early withdrawal from a 401(k) or similar plan or IRA.
- Twenty-eight percent of Baby Boomer workers have a written financial strategy for retirement, while 15% frequently discuss saving, investing, and planning for retirement with family and close friends.
Strengthening Retirement Security
“Retirement security is a shared responsibility among policymakers, employers, and individuals. A strong U.S. retirement system requires a robust economy, a vibrant labor market, access to workplace retirement plans, and an affordable cost of living,” said Collinson. “Everyone should have the ability to retire with dignity. Success depends on workers’ ability to earn income, support their families, and save for the future. It also depends on the strength of Social Security and Medicare, which face long-term funding issues.”
Stressed and Strained: Four Generations Strive for Retirement Security is part of the 26th Annual Retirement Survey, one of the largest and longest-running surveys of its kind. It provides recommendations for workers, employers, and policymakers. To download the report, visit www.transamericainstitute.org. Follow on LinkedIn, Facebook, and X @TI_insights and @TCRStudies.
About Transamerica Center for Retirement Studies
Transamerica Center for Retirement Studies (TCRS) is a division of Transamerica Institute, a nonprofit, private operating foundation. TCRS conducts one of the largest and longest-running annual retirement surveys of its kind. The information provided here is for educational purposes only and should not be construed as insurance, securities, ERISA, tax, investment, legal, medical, or financial advice or guidance. Please consult independent professionals for answers to your specific questions. www.transamericainstitute.org
About the 26th Annual Transamerica Retirement Survey
The analysis contained in Stressed and Strained: Four Generations Strive for Retirement Security was prepared internally by the research team at Transamerica Institute and TCRS. The research was conducted online in the U.S. by The Harris Poll on behalf of Transamerica Institute and TCRS among 6,153 workers in a for-profit company employing one or more employees. The survey was conducted September 16-October 17, 2025. Data are weighted where necessary by age by gender, race/ethnicity, region, education, marital status, household size, household income, and smoking status to bring them in line with their actual proportions in the population. Respondents for this survey were selected from among those who have agreed to participate in our surveys. The sampling precision of Harris online polls is measured by using a Bayesian credible interval. For this study, the sample data is accurate to within ±1.8 percentage points using a 95% confidence level. This credible interval will be wider among subsets of the surveyed population of interest. All sample surveys and polls, whether or not they use probability sampling, are subject to other multiple sources of error which are most often not possible to quantify or estimate, including, but not limited to coverage error, error associated with nonresponse, error associated with question wording and response options, and post-survey weighting and adjustments.
Media Contact: Kyle Moschen
kyle.moschen@omc.com
 View original content to download multimedia:https://www.prnewswire.com/news-releases/inflation-competing-priorities-and-uncertainty-erode-retirement-security-302921686.html
SOURCE Transamerica Institute


